Key Considerations When Retiring to Portugal
Reviewed by Ed WilkinsonLast updated: June 5, 2026 9:50 am
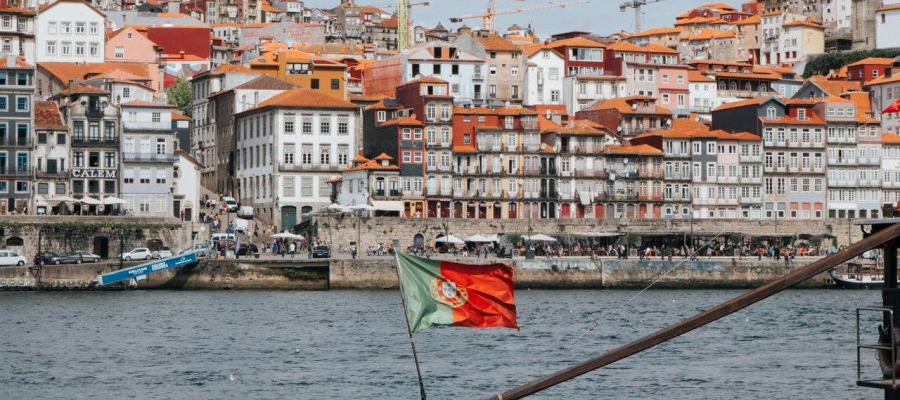
Image credit: by Natallia @Pexels
In this article:
Retiring to Portugal combines European charm, a mild climate and a relaxed pace of life. As with any international move, planning is essential. The points below outline practical steps and considerations to help you assess whether a move to Portugal fits your circumstances.
Understanding Residency Requirements
The first step is to understand how to obtain residency. Non‑EU/EEA/Swiss citizens (including UK nationals) generally need a residence visa before moving. Many retirees use the D7 (Passive Income) visa1, which requires demonstrating stable income from sources such as pensions, investments, rentals or royalties. As a rule of thumb, consulates expect proof of funds broadly in line with the Portuguese minimum wage for the main applicant, with additional amounts for a spouse/partner and dependent children. Thresholds and evidential requirements are updated periodically and can vary by consulate, so check the latest guidance from Portugal’s immigration authority2 before applying. On arrival, you apply for a residence permit and must show suitable accommodation and sufficient means to support yourself.
Additional Documentation and Renewal Criteria
After arriving, the residence permit process typically involves: proof of accommodation (rental agreement or title deed), valid health cover (private insurance or eligibility via an S1 form3), clean criminal record certificates, proof of income and bank statements, a Portuguese tax number (Número de Identificação Fiscal, NIF4) and, in some cases, a Portuguese bank account. The initial residence permit is usually valid for two years and can be renewed for a further three years. After five years of lawful residence, you may apply for permanent residency; eligibility for citizenship is a separate process with additional criteria (including a Portuguese language requirement5).
Healthcare Registration Process
Once settled, register at your local health centre to obtain access to Portugal’s National Health Service6 (Serviço Nacional de Saúde, SNS). UK State Pension recipients may be eligible for an S1 certificate, which can grant access to state healthcare in Portugal paid for by the UK. The SNS provides broad coverage with modest co‑payments, and many expatriates also take out private health insurance to reduce waiting times and expand provider choice.
Opting for Comprehensive Health Insurance
When comparing private health insurance, consider nationwide networks, direct billing, cover for pre‑existing conditions and medical repatriation. Take time to review policy exclusions, waiting periods and annual limits, and seek impartial guidance if you are unsure what level of cover is appropriate.
Preparing your documentation in advance, understanding AIMA’s current rules and arranging suitable health cover will make your transition smoother and help ensure you remain compliant with Portuguese residency requirements.
Cost of Living and Financial Planning
Portugal’s cost of living is generally lower than in many Western European countries, though it varies markedly by region and lifestyle. Typical expenses include housing, food, healthcare, transport and leisure. It is also important to understand how your income will be taxed in Portugal and in your home country, and how exchange rates could affect your budget. If you will rely on a UK State Pension, note that the current State Pension age7 is 66 and is scheduled to rise to 67 between 2026 and 2028; the State Pension can usually be paid abroad and is currently uprated annually for residents in EU countries. Consider seeking regulated, cross‑border financial and tax guidance to assess your position.
Assessing the Tax Landscape
Portugal taxes residents on their worldwide income. A double tax treaty between the UK and Portugal8 helps prevent the same income being taxed twice, but you may still need to file in both countries.
- Portugal operates progressive income tax rates up to 48%9 (bands and rates change periodically, and additional surcharges may apply in some cases). Check the current tables for the year you become tax resident.
- Portugal’s former Non‑Habitual Resident (NHR) regime closed to most new applicants from 2024. Transitional rules apply in limited circumstances, and those already within NHR generally keep their status for the remainder of their 10‑year period. New residents are usually taxed under the standard rules.
- There is no general inheritance or gift tax, but stamp duty (Imposto do Selo10) at 10% applies to most gratuitous transfers of Portuguese‑sited assets. Transfers to spouses, civil partners, descendants and ascendants are usually exempt.
Choosing the Right Location
Your choice of location will shape your daily life and budget. The Algarve is popular with retirees for its climate and established expatriate communities. Lisbon and Porto offer rich culture and amenities, but at a higher cost. Central and northern regions can provide a quieter pace of life and lower living costs.
Cost Comparisons Between Regions
When considering where to settle, it can help to compare indicative monthly budgets:
- In the Algarve, a typical budget for a couple might be around €1,500, covering rent, groceries, and routine expenses.
- In Lisbon, this could rise to approximately €2,500 due to higher housing and entertainment costs.
- In cities such as Coimbra or Viseu, a careful budget of around €1,200 a month may be achievable, depending on housing choices.
Each region offers distinct lifestyle benefits. Speaking with local residents and expatriate groups and testing a budget for short‑term accommodation before committing can provide useful, real‑world insight.
Careful planning and, where appropriate, regulated advice can help you build a sustainable retirement plan in Portugal that reflects your resources, goals and risk tolerance.
Real Estate Considerations
Retirees can choose to rent or buy. Property prices have risen in recent years, especially in prime areas of Lisbon, Porto and the Algarve. Prices vary widely by neighbourhood, property type and condition. Renting first is often sensible so you can compare areas and market conditions before committing capital. If you plan to buy, familiarise yourself with local property law and taxes and consider appointing an independent lawyer to represent your interests.
Understanding Property Laws and Taxes
The purchase process typically involves obtaining a NIF (tax number), conducting due diligence, signing a promissory contract, completion before a notary and registration at the Land Registry. Ongoing property taxes include IMI (municipal property tax). High‑value properties may also be subject to the additional property tax (AIMI). An experienced legal adviser can help you navigate the process and ensure compliance.
Benefits of Renting Before Buying
Renting first offers flexibility to explore different communities and climates, from the Algarve’s coastline to Porto’s historic neighbourhoods, before deciding where to settle. It also gives you time to monitor market movements and understand running costs (such as condominium fees and utilities) before purchasing.
Integration into the Community
Integrating into the local community will enhance your retirement experience. Learning basic Portuguese helps with daily interactions and shows respect for local culture. Joining clubs, classes and volunteering are effective ways to build a social network.
Engaging with Local Culture and Community
Participating in local events, markets and traditional festivals can enrich your experience and deepen your connection to Portuguese life. Many towns host regular cultural activities that provide opportunities for social interaction and cultural immersion.
By carefully weighing these real estate and community factors, you can make informed decisions that support a comfortable and fulfilling life in Portugal.
Transportation and Mobility
Portugal offers a broad range of transport options, which matter when assessing accessibility and day‑to‑day convenience. The national network includes buses, intercity and regional trains and, for longer distances, reasonably priced domestic flights.
Public Transport in Urban Areas
In major cities like Lisbon and Porto, public transport is extensive, including metro, trams, buses and taxis. Lisbon’s metro spans over 40 km across four lines and connects key areas of the city, providing an efficient way to get around. Historic trams operate on several routes and are both a practical and scenic way to experience the city.
Transport Considerations in Rural Areas
Rural areas often have less frequent services, so owning a car can be more practical. If you plan to drive, familiarise yourself with local rules: traffic keeps to the right and road signs follow European conventions. Ensure your driving licence is valid in Portugal and check insurance requirements.
Cost and Accessibility of Public Transport
Public transport costs compare favourably with those in many Western European countries. A monthly metropolitan pass in the Lisbon area costs around €40- €80.11
Integration of Technology in Transportation
Most urban areas offer journey‑planning apps with real‑time updates for buses, trams and trains, helping you plan efficiently and reduce waiting times.
When selecting a location, consider proximity to shops, healthcare and transport, and how these align with your lifestyle. Whether you value the convenience of a dense urban network or the quieter pace of rural living, Portugal offers options to suit different needs.
A Financial Adviser Can Help
Retiring abroad affects pensions, investments, taxes and estate planning across at least two jurisdictions. A regulated adviser with cross‑border experience can help you understand your options, how the UK–Portugal double tax treaty may apply, and how to structure your income sustainably. This article is for information only and does not constitute personal advice.
FinancialAdvisers.co.uk can connect you with a Financial Conduct Authority (FCA) authorised adviser in your area who has experience with expatriate planning. Always check an adviser’s status on the FCA Register and make sure any recommendations are tailored to your circumstances before acting.
This article contains external links for further information on topics. Whilst all attempts are made to verify the trustworthiness of these external sources, we accept no responsibilty for the upkeep or security of these external websites. Some of these links in particular are annotated below:
- 1 https://www.sovereigngroup.com/portugal/portugal-passive-income-d7-visa/
- 2 https://aima.gov.pt/pt
- 3 https://overseas-healthcare.nhsbsa.nhs.uk/apply-healthcare-cover-living-abroad/start
- 4 https://www2.gov.pt/en-GB/servicos/pedir-o-numero-de-identificacao-fiscal-para-pessoa-singular
- 5 http://goldenvisas.com/portugal-golden-visa-citizenship-understanding-the-language-requirement
- 6 https://www.gov.uk/guidance/healthcare-in-portugal-including-madeira
- 7 https://www.ageuk.org.uk/information-advice/money-legal/pensions/state-pension/changes-to-state-pension-age/
- 8 https://www.gov.uk/government/publications/portugal-tax-treaties/2025-uk-portugal-double-taxation-convention-not-in-force
- 9 https://taxsummaries.pwc.com/portugal/individual/taxes-on-personal-income
- 10 https://www.cgd.pt/Site/Saldo-Positivo/leis-e-impostos/Pages/o-que-e-o-imposto-do-selo.aspx
- 11 https://www.metrolisboa.pt/en/buy/