
Is Pension Cold Calling Illegal?
Reviewed by Ed WilkinsonLast updated: May 8, 2026 4:31 pm
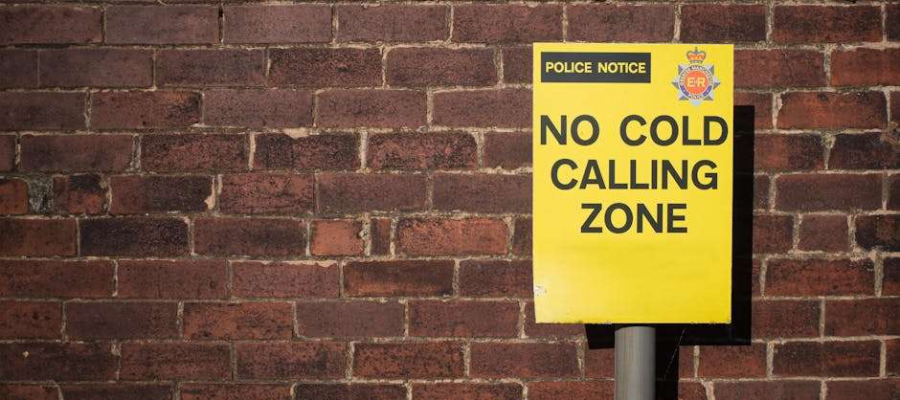
Image credit: James Thomas @Pexels
In this article:
In the UK, pension cold calling has become a significant concern due to the increasing number of scams targeting pension funds. This has prompted legal measures and regulations to curb the prevalence of unsolicited calls. Understanding the legal landscape surrounding pension cold calling not only helps protect individuals’ pensions but also informs them how to handle such situations appropriately. This article explains the rules, the limited exceptions, and practical steps to take if you receive such a call. It is provided for general information only and does not constitute financial advice.
Understanding Pension Cold Calling
Pension cold calling typically involves receiving an unsolicited call from a company or individual offering pension services or investment opportunities. These calls are not only intrusive but can also lead to substantial financial loss if they result in pension scams. Recognising the potential dangers, the UK government has implemented strict legal restrictions on such practices to safeguard consumers. Although the specific ban targets phone calls, texts, and emails, pension-related communications are also tightly regulated under PECR and the UK GDPR and should be treated with caution.
Impact of Pension Cold Calling
Victims of pension scams can suffer large, sometimes life-changing losses. Cold calls are a common tactic used by fraudsters, who may use persuasive or aggressive techniques to pressure people into transferring or investing their pension savings.
Regulatory Measures and Their Effectiveness
Since the introduction of the ban on pension cold calls in 20191, enforcement action and industry warnings have helped reduce opportunities for scammers, but criminals continue to adapt. Remaining vigilant is essential; never assume a call is legitimate simply because the caller knows personal details.
Recognising Legitimate Calls
It is crucial for individuals to distinguish between legal and illegal cold calls. In general, legitimate direct marketing calls about pensions may only be made when: the caller is authorised by the FCA (or is a trustee/manager of a pension scheme); and the recipient has given specific consent to receive such calls, or there is an existing client relationship, and the caller has reasonable grounds to believe the recipient expects calls about pensions. If any of these conditions are not met, the call is likely unlawful. Genuine firms should not pressure you and will be happy for you to call back on a published number.
Preventive Actions to Take
If you receive a pension cold call, acting cautiously is paramount. First, verify the caller’s legitimacy independently by contacting the company they claim to represent using officially listed phone numbers, and by checking the firm and individuals on the FCA Financial Services Register2 and the FCA Warning List3. Second, be wary of sharing personal financial information; legitimate firms will understand and respect privacy concerns. It is perfectly acceptable to hang up, wait, and call back on a number you have sourced yourself.
By staying informed about how the ban works and the common features of pension cold calls, you can better protect yourself from potential scams and help safeguard your retirement savings.
Legal Status of Pension Cold Calling in the UK
Since January 2019, the UK government has enforced a ban on pension cold calls, making it illegal for any entity to make unsolicited calls regarding individuals’ pensions in most situations. This ban sits within the Privacy and Electronic Communications Regulations4 (PECR) and is enforced by the Information Commissioner’s Office5 (ICO). Breaches can lead to substantial fines. The ban applies to calls made to UK consumers regardless of where the caller is located. While it specifically targets phone calls, texts and emails are also tightly controlled under PECR and UK GDPR.
Clarifying the Exceptions to the Ban
While the general rule prohibits unsolicited pension calls, there are specific conditions under which such calls are still permissible. These exceptions aim to balance consumer protection with the practical aspects of financial communication and services.
- The caller must be authorised by the Financial Conduct Authority (FCA), or be a recognised trustee or manager of a pension scheme (this is a mandatory condition).
- In addition, the recipient must have explicitly consented to receive these calls from the specific caller.
- Alternatively, there must be an existing client relationship, and the caller must have reasonable grounds to believe the recipient expects calls about pensions.
Statistical Overview and Ongoing Monitoring
Regulators report and act against unlawful pension marketing and scams. The ICO can investigate and fine firms for unlawful direct marketing, while the FCA can act against authorised firms that breach conduct rules. Both bodies monitor emerging tactics and update consumer warnings to reflect new threats.
The ongoing commitment by regulatory bodies to refine and enforce these laws is vital in maintaining the integrity of the financial services sector and protecting individual investors. By staying informed about the legal context and the exceptions to the ban, individuals can better understand and manage unsolicited calls related to their pensions.
Increased Public Awareness
Alongside legislative measures, increased public awareness and education about pension scams and the conditions under which pension cold calls are legal play a crucial role in safeguarding the public. The FCA and related organisations continue to run public awareness campaigns to educate pension holders about their rights and the potential red flags associated with pension fraud.
This comprehensive approach, combining legal restrictions, ongoing monitoring, and public education, ensures that individuals are not only protected by law but are also empowered to protect themselves against potential scams.
What to Do If You Receive a Pension Cold Call
If you receive a pension cold call, it is crucial to proceed with caution. Here are some steps you can take:
- Do not disclose personal information: Never give out personal financial details over the phone, especially to an unsolicited caller. Scammers often use sophisticated tactics to appear legitimate, so it’s essential to be vigilant.
- Verify the caller: If the caller claims to be from a legitimate organisation, verify this by contacting the organisation directly using contact details you trust, such as those from their official website. Do not use any contact details provided by the caller, as these could be part of the scam. Check the firms and individuals on the FCA Financial Services Register and the FCA Warning List.
- Report the call: Report unsolicited pension marketing calls to the Information Commissioner’s Office (ICO) as a PECR breach. If you suspect a scam or have transferred money, also report it to the FCA (via its ScamSmart pages6 or consumer helpline) and to Action Fraud7 (the UK police reporting centre) online.
- Seek advice: If you’re unsure about the legitimacy of a call or the information provided, consult a financial adviser who is authorised and regulated by the FCA. A professional can offer guidance and help you understand your pension rights and options. You can check an adviser’s status on the FCA Register.
Additional Precautions
Besides the immediate steps listed above, consider these additional precautions to enhance your protection against pension scams:
- Register with the Telephone Preference Service (TPS) to reduce the number of unsolicited calls you receive. This free service is designed to help UK consumers manage their preferences regarding telemarketing calls, but note that it will not block criminals making illegal calls.
- Regularly review your pension statements and accounts for any unusual activity or unauthorised changes. Early detection of discrepancies can prevent significant losses.
- Educate yourself about the common signs of pension scams, such as promises of guaranteed high returns or pressure to make quick decisions. The FCA website (including ScamSmart) offers resources and updates on known scam techniques and preventive tips.
Stay Informed
Keeping up to date with the latest regulations and known scam tactics is crucial. The FCA and ICO periodically update their guidelines and offer resources that help consumers recognise and avoid scams. By staying informed and by using the FCA Financial Services Register and Warning List to check firms and individuals, you can better safeguard your finances against potential threats.
Recognising Pension Scams
Pension scams can be sophisticated and convincing, employing various tactics to deceive. It is crucial to recognise these red flags:
- Offers of a ‘free pension review’, ‘one-off investment opportunities’, ‘legal loopholes’, or early access to your pension before the minimum pension age8 (usually 55, rising to 57 from 6 April 2028) that sound too good to be true.
- High-pressure sales tactics that urge you to make quick decisions, often accompanied by time-limited offers.
- Promises of unusually high returns on your pension investment, far above the market average.
- Requests to transfer your pension money to an overseas scheme or an unfamiliar provider without clear, verifiable credentials.
- Unsolicited contact, via phone, email, or in person, especially when the entity does not have prior permission to contact you.
Identifying Less Obvious Scam Tactics
Scammers often use less direct methods to gain trust and appear legitimate:
- Use of technical jargon or complex financial terminology intended to confuse and overwhelm the recipient.
- Proposing investments in unconventional ‘guaranteed’ schemes like rare metals, overseas property, or renewable energy projects.
- Impersonating legitimate companies or government bodies, complete with fake documents bearing official-looking logos and language.
Statistical Insights
Regulators regularly warn that approaches such as ‘free pension reviews’ are common precursors to scams. Be cautious of anyone offering seemingly credible ‘inside information’ or ‘exclusive tips’. Awareness and vigilance remain key.
Immediate Actions If You Suspect a Scam
If you encounter any of the above warning signs, take these steps without delay:
- Do not proceed with any transaction or disclose personal information.
- Contact the FCA’s consumer helpline or visit their website to verify the legitimacy of the company and the offer (use the FCA Register and Warning List).
- Report the incident to the FCA to help prevent further scams, and report to Action Fraud. If you think you may have transferred money or information, contact your pension provider and bank immediately to try to stop or recover funds.
Staying informed about the characteristics of pension scams and understanding the tactics scammers use can significantly enhance your ability to safeguard your finances. Regular updates from the FCA and pension advisory services are invaluable resources for staying aware of potential threats.
A Financial Adviser Can Help
Consulting with a professional financial adviser can provide clarity and security when managing your pension. Financial advisers can offer personalised advice that aligns with your financial needs and helps you navigate the complexities of pension decisions. They can also assist you in identifying legitimate opportunities and avoiding potential scams. Charges will apply, so ask for a clear explanation of fees and services.
Moreover, a qualified financial adviser can guide you on the appropriate actions to take if you’ve been targeted by a pension cold call, including how to protect your assets and report the incident to the proper authorities. Always check that the adviser and firm are authorised and regulated by the FCA by using the Financial Services Register.
If you need help with pension management, avoiding scams, or dealing with the aftermath of a pension cold call, you can use a directory or matching service such as FinancialAdvisers.co.uk. Whichever route you take, verify that the firm or individual is an FCA-authorised financial adviser by checking the Financial Services Register. We do not endorse any particular service.
This article contains external links for further information on topics. Whilst all attempts are made to verify the trustworthiness of these external sources, we accept no responsibilty for the upkeep or security of these external websites. Some of these links in particular are annotated below:
- 1 https://www.gov.uk/government/news/pensions-cold-calling-banned
- 2 https://www.fca.org.uk/firms/financial-services-register
- 3 https://www.fca.org.uk/consumers/warning-list-unauthorised-firms
- 4 https://www.legislation.gov.uk/uksi/2003/2426/contents
- 5 https://ico.org.uk/
- 6 https://www.fca.org.uk/consumers/protect-yourself-scams
- 7 https://www.reportfraud.police.uk/
- 8 https://www.gov.uk/government/publications/increasing-normal-minimum-pension-age/increasing-normal-minimum-pension-age


