What Is Second Home Premium Council Tax?
Reviewed by Ed WilkinsonLast updated: July 21, 2026 11:30 am

Image credit: Thirdman @Pexels
In this article:
In recent years, the landscape of property ownership in the UK has seen significant changes, particularly in the policies affecting second homes. One notable development has been the introduction and expansion of council tax premiums for second homes. These premiums are intended to address issues ranging from local housing shortages to the impact of holiday homes on community resources. This guide explains how second-home Council Tax premiums work, what they may mean for property owners, and how they fit into wider housing policy.
Understanding Second Home Premium Council Tax

Image credit: Pavel Danilyuk* @Pexels
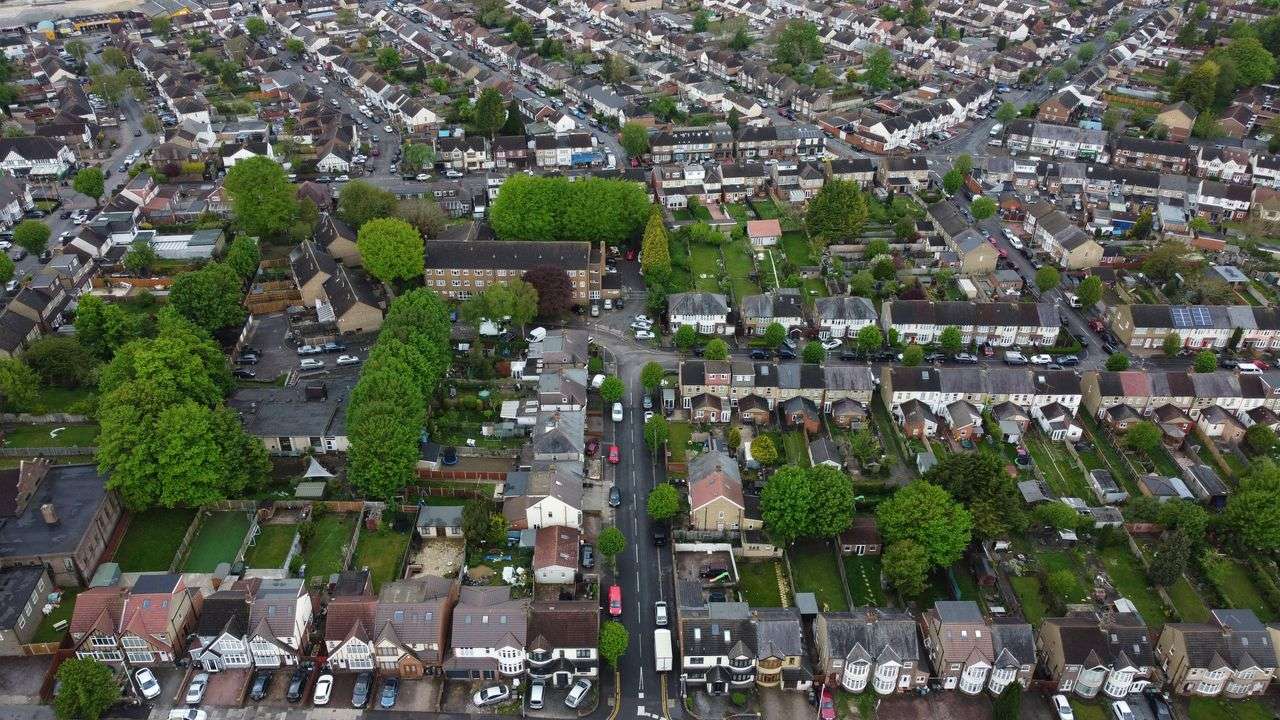
A council tax premium on second homes is an additional charge that local authorities may apply to furnished dwellings that are not used as anyone’s sole or main residence. The powers and limits differ across the UK nations. In England, under the Levelling-up and Regeneration Act 20231, councils can apply a premium of up to 100% (i.e., double the standard bill) from 1 April 2025, provided they give at least 12 months’ notice. In Wales, councils have been able to charge premiums of up to 300% since April 2023. In Scotland, councils may charge up to a 100% premium from 1 April 2024. Northern Ireland does not have Council Tax and operates a separate domestic rates system.
Criteria for Defining a Second Home
For Council Tax purposes, a second home is typically a property that is substantially furnished and not your sole or main residence. Councils may consider evidence such as where you spend most of your time, where you are registered to vote, and patterns of utility use when determining your main residence. Certain statutory exceptions and discounts can apply (for example, some job-related dwellings or annexes), so it is important to check your local council’s published rules.
Regional Variations in Premium Charges
The level of any premium is set locally, reflecting housing pressures and policy objectives. Councils in areas with high demand from holiday homes or short-term lets may adopt higher rates, while others apply lower or no premiums. For example, several Welsh coastal and national park authorities have set premiums between 150% and 300% for second homes, while some English and Scottish councils have opted for the upper limit of 100%.
Implications of Rising Premiums
- Economic Impact: Higher premiums may encourage owners to bring properties into fuller use (for example, by letting on a longer-term basis), potentially increasing local housing supply.
- Revenue Generation: Premium income forms part of councils’ general funding to support local services; allocations and impacts will vary locally.
Administrative Considerations
Administering premiums requires councils to carefully monitor and categorise properties so that second homes are accurately identified and billed. Although this involves administrative effort, it is crucial for effective implementation.
Property owners should stay informed about the specific requirements and rates in their council area to manage their obligations and comply with local regulations. In England, councils must give at least 12 months’ notice before a second-home premium starts or changes. This attention to detail helps ensure that premiums meet their aims while fairly distributing tax burdens.
Impact on Homeowners and Local Communities
The implementation of second-home Council Tax premiums has significant implications for both homeowners and the communities in which these properties are located.
Financial Implications for Property Owners
- Increased Financial Burden: Homeowners with second properties are required to pay a higher Council Tax, which can be substantially higher than the standard rate, depending on the council’s chosen premium. In England and Scotland, premiums can be up to 100% (doubling the standard bill); in parts of Wales, some councils have set premiums as high as 300%, which can materially affect owners’ budgeting.
- Property Management Decisions: The additional cost can influence decisions about keeping, renting or selling a second home. Some owners may choose to let properties to offset the higher bill, while others might consider selling if running costs and premiums erode the benefits of ownership.
Benefits to Local Communities
- Reduced Housing Pressures: By disincentivising the underuse of homes, premiums may help bring more properties to the long-term rental or sales market, potentially easing local housing pressures in areas with a high concentration of second homes.
- Support for Local Services: Additional Council Tax revenue contributes to councils’ general funding and can support local services. The precise use of funds will vary by authority and is not ring-fenced.
Enhanced Community Engagement and Stability
Premiums can encourage a more consistent year-round population by reducing the number of underused properties, thereby supporting stronger neighbourhood ties and social cohesion over time.
Administrative Efficiency and Transparency
For premiums to achieve their intended effects, councils should ensure efficient and transparent administration. Clear communication with property owners about how premiums operate can foster greater acceptance and compliance.
Considerations for Future Adjustments
As housing markets and local economic conditions evolve, councils may need to reassess premium levels. The aim is to balance discouraging underuse with the need to avoid unduly penalising second-home owners, particularly during economic downturns or market shifts.
Strategic Considerations and Challenges

Image credit: Kindel Media* @Pexels
The introduction of second-home Council Tax premiums presents practical and strategic considerations. For councils, setting the right level involves balancing additional income against possible behavioural responses. Property owners, meanwhile, must weigh the financial implications when deciding how to use or retain second homes.
Calculating the Premium
Each local authority has discretion to set its premium rate, so bills can vary markedly between areas. Homeowners must check with their local council to understand the rates that apply. As of 2026, second-home premiums are generally set as a single percentage by each council. Separate rules apply to long-term empty properties, where higher premiums can apply the longer a property has been empty; these should not be confused with second-home premiums.
Legal and Administrative Challenges
Implementing and managing premiums requires robust processes so that properties are correctly categorised and billed. Councils must also ensure policies are consistent with legislation and any statutory exemptions, and that they provide clear routes for queries and appeals.
Impact on Local Investment
High premium rates may deter some potential purchasers of second homes, thereby cooling local markets. Councils should weigh short-term revenue benefits against long-term objectives for housing availability, community sustainability and investment.
Economic Analysis and Forecasting
To help set appropriate rates, councils may use economic analysis and forecasting to assess likely impacts on the housing market and the wider local economy. Evidence-led decisions are more likely to align with community needs and statutory duties.
Administrative Efficiency and Transparency
To enhance trust and compliance, councils should provide clear guidance, publish policy decisions in good time and report on outcomes where possible. Accessible channels for homeowners to query their status and understand obligations are essential.
Guidance for Property Owners
Local councils are encouraged to provide practical tools and guidance (such as online information and contact points) to help owners navigate premium costs. If you let a property commercially, it may be liable for business rates rather than Council Tax, subject to specific criteria that vary across the UK. Always check your council’s rules and consider seeking professional advice if your circumstances are complex.
A Financial Adviser Can Help
Navigating second-home Council Tax premiums requires understanding local policy and your broader financial position. A regulated financial adviser can help you assess how premiums affect your cash flow and long-term plans, and consider options such as renting, selling or retaining a property in the context of your goals and risk tolerance.
Depending on your needs, you may also wish to consult your local council or a qualified tax professional for guidance on liability, exemptions and interactions with other taxes. Any decision should be based on your personal circumstances.
FinancialAdvisers.co.uk can help you connect with an FCA-authorised and regulated financial adviser in your area who can provide personalised advice. Whether you are considering purchasing a second home or already own one, professional advice can help you make informed, balanced decisions. Nothing here is personal advice, and rules and thresholds can change; always check current guidance with your local council.
This article contains external links for further information on topics. Whilst all attempts are made to verify the trustworthiness of these external sources, we accept no responsibilty for the upkeep or security of these external websites. Some of these links in particular are annotated below:
The following domains are also linked to credit authors and/or photographers: