EBITDA in Accounting and Corporate Finance
Reviewed by Neil AinsworthLast updated: February 16, 2026 2:32 pm

Image credit: Karolina Grabowska www.kaboompics.com @Pexels
In this article:
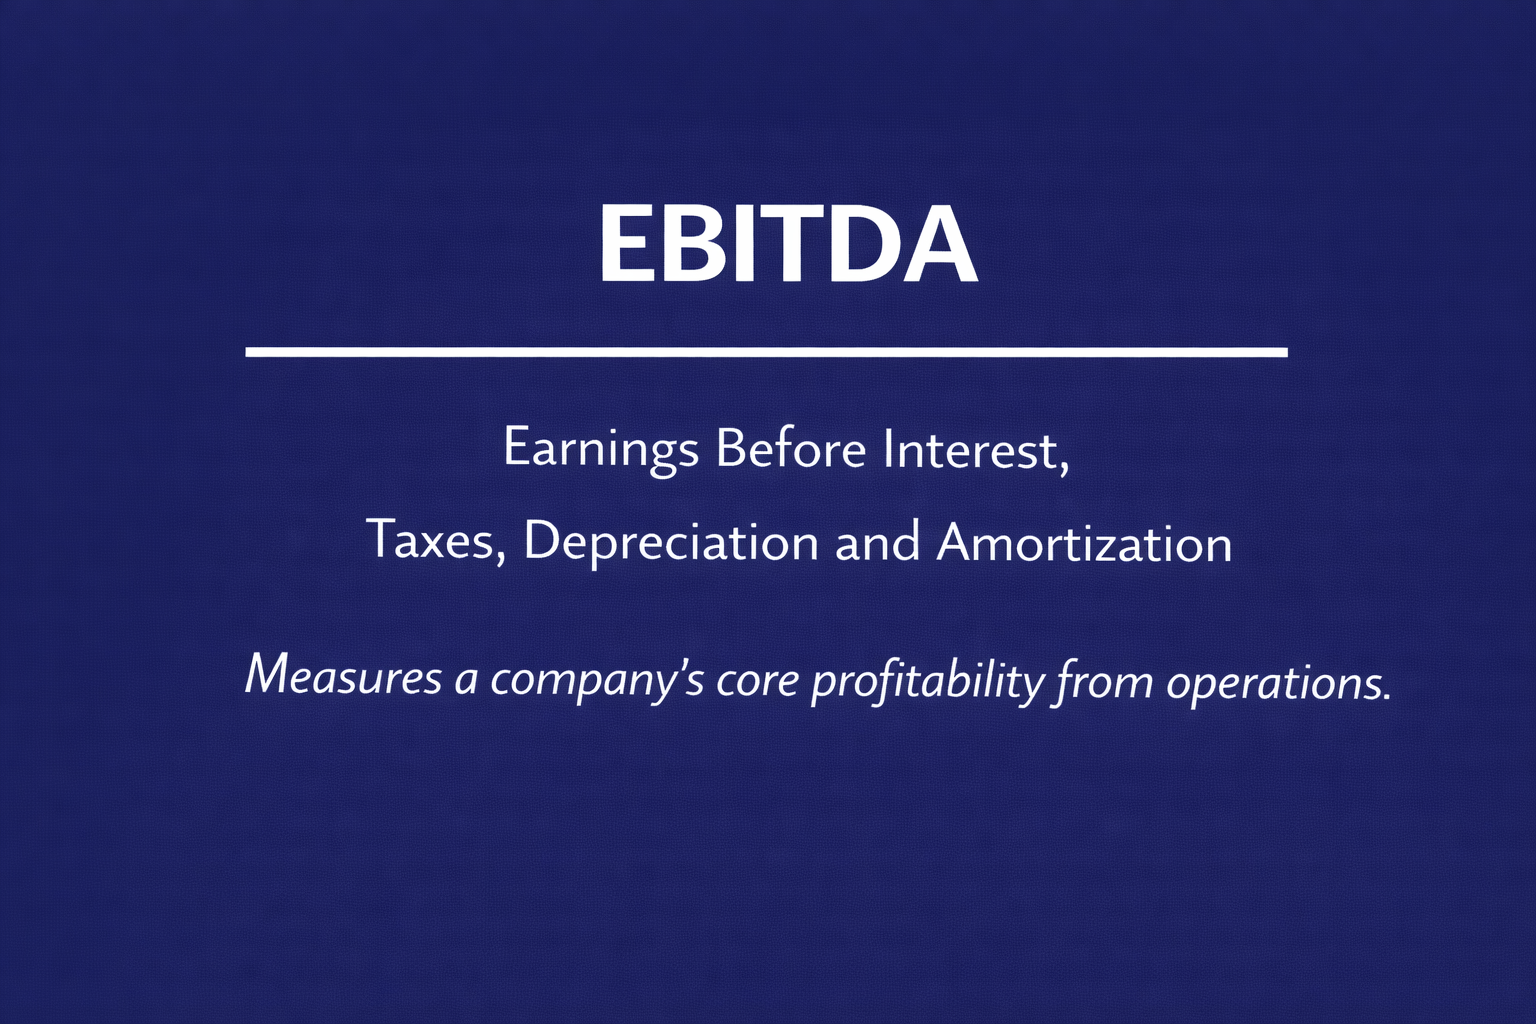
EBITDA, an acronym for Earnings Before Interest, Taxes, Depreciation and Amortisation, is a widely used metric in accounting and corporate finance for assessing a company’s operating performance. This indicator helps investors and analysts evaluate a company’s profitability before the impact of financing, accounting and tax effects. It is an alternative performance measure rather than a statutory metric under IFRS, so definitions can vary between companies. Understanding EBITDA and its implications is useful for anyone involved in business management or financial analysis.
Understanding EBITDA
EBITDA serves as a tool to analyse and compare profitability between companies and industries because it strips out the effects of financing and certain accounting decisions. By removing interest, taxes, depreciation and amortisation, EBITDA focuses on operating earnings, making it easier to compare companies with different capital structures and tax situations. This can help stakeholders assess operational efficiency, though it is not a cash flow measure and should be interpreted alongside other information.
Components of EBITDA Explained
- Interest: EBITDA removes the cost of debt financing, which can vary significantly among companies depending on their capital structure. For instance, a company heavily reliant on debt will have high interest expenses, which are excluded from EBITDA, providing a clearer picture of operational performance irrespective of financing choices.
- Taxes: It excludes taxes, which can differ greatly between different jurisdictions and tax strategies. This exclusion is particularly useful for multinational corporations operating across various tax regimes, thereby facilitating a more uniform analysis of business performance.
- Depreciation and Amortisation: These accounting practices spread the cost of tangible and intangible assets over their useful lives. By excluding these figures, EBITDA provides a view of operating performance that’s not influenced by these long-term allocations. This is important in industries where heavy capital investments are made, such as manufacturing and telecommunications.
Additional Insights into EBITDA’s Role
Understanding EBITDA in the context of operational performance also involves recognising its role in mergers and acquisitions. Companies often look at EBITDA as a gauge to estimate potential synergies and the operational upside of a merger. When interest rates fluctuate, EBITDA can help isolate operating earnings from financing costs, aiding comparability over time. However, financing conditions may still influence strategy and demand, so EBITDA should not be viewed in isolation.
Furthermore, during periods of economic uncertainty it can offer a view of core operating performance that is less affected by financing and tax charges. Inflation, input costs and pricing still flow through to revenues and operating expenses, so movements in EBITDA should be interpreted in that wider context.
In summary, while EBITDA is a useful tool for analysis, it should be considered alongside other metrics to build a comprehensive understanding of a company’s financial position and prospects.
Calculating EBITDA
To calculate EBITDA, you begin with the net income of a company, then make adjustments for certain expenses not directly related to core business operations. This calculation removes the effects of financing and some accounting decisions, providing an indicator of operating profitability. Many analysts also start from operating profit (EBIT) and add back depreciation and amortisation; both approaches should lead to the same result if applied consistently. Here is a detailed breakdown of the formula:
- Start with Net Income: This is the company’s profit after all expenses have been deducted from revenues.
- Add back Interest Expense: This includes all costs related to debt, such as bank loans or bonds issued by the company. Interest costs can fluctuate with market rates and a company’s capital structure, which would otherwise affect net income.
- Add back Taxes: This adjustment removes the influence of tax charges, which can vary widely depending on corporate tax strategies and changes in legislation.
- Add back Depreciation and Amortisation: These non-cash expenses spread the cost of tangible and intangible assets over their useful lives and can vary depending on the accounting policies adopted.
This calculation gives a clearer picture of operating performance from core activities. It is not a measure of cash generation, as it excludes movements in working capital, capital expenditure, lease payments and other cash requirements.
Additional Considerations
When calculating EBITDA, it’s also important to consider any irregular revenues or expenses that might distort the understanding of a company’s ongoing profitability. Examples include one-off sales of assets, restructuring costs, or unusually large legal expenses. Adjusting for these items can provide a more consistent and repeatable measure of core operational performance. Such adjustments are often described as adjusted or normalised EBITDA; definitions can vary, so reconciliations to statutory figures should be provided. Under IFRS 161, operating lease costs are split between depreciation and interest, which tends to increase EBITDA compared with pre-IFRS 16 reporting, so care is needed when comparing across periods or companies. Items such as share-based payment expenses are operating costs and should only be adjusted if clearly justified and transparently disclosed.
Overall, while EBITDA provides useful insight into a company’s operational performance, it should be used in tandem with other financial metrics to get a comprehensive view of the company’s financial health. The FCA expects communications to be fair, clear and not misleading; presenting multiple metrics with clear explanations supports a balanced assessment.
Uses of EBITDA
EBITDA is particularly useful in several financial contexts:
- Investment Analysis: Investors rely on EBITDA to compare the financial performance of companies without the distortion of accounting and financial obligations. It facilitates a clearer, more consistent comparison across different sectors and geographical regions, enabling investors to make informed decisions based on operational performance. It should be considered alongside cash conversion, capital expenditure requirements and leverage.
- Loan Covenants: Lenders frequently utilise EBITDA to evaluate a company’s ability to service debt. It is a crucial metric in loan agreements and debt covenants, often dictating the terms under which loans can be granted or maintained. Common covenant ratios include net debt to EBITDA and interest cover, which help assess debt-servicing capacity.
- Valuation: EBITDA serves as a foundational element for calculating the enterprise value of a business through EBITDA multiples, including EV/EBITDA. This is particularly prevalent in industries where cash flow stability is a key valuation driver, such as utilities and telecommunications.
EBITDA Margin
The EBITDA margin, calculated by dividing EBITDA by total revenue, offers insight into a company’s operational efficiency. A higher EBITDA margin implies more efficient operations and a stronger ability to generate cash from sales revenues. This metric is especially useful for internal comparisons over different periods or against industry peers to gauge performance improvements or declines. Ensure like-for-like definitions are used (for example, reported versus adjusted EBITDA) when making comparisons.
Additional Applications of EBITDA
In addition to its primary uses, EBITDA is instrumental in strategic planning and operational adjustments. Management teams employ EBITDA to identify areas within their operations that require enhancement or may be performing exceptionally well. This operational metric is often linked to performance benchmarks in managerial incentive plans, underlining its importance in strategic management and operational focus.
- Benchmarking: Companies often use EBITDA to set internal performance benchmarks. By comparing EBITDA margins to those of industry leaders, companies can identify operational inefficiencies and target improvements.
- Performance Incentives: EBITDA is frequently integrated into executive compensation structures to align management’s interests with those of shareholders, focusing on sustainable operational success. Where used, definitions and adjustments should be transparent.
While EBITDA provides insights into a company’s financial operations, it should be interpreted with an understanding of its limitations. Regulatory expectations emphasise balanced presentation, with supplementary financial metrics and reconciliations used alongside EBITDA to provide a comprehensive view of a company’s financial health.
Limitations of EBITDA
While EBITDA is beneficial, it has limitations and should be used cautiously:
- Not a Cash Flow Measure: EBITDA is not a measure of cash flow because it does not account for the cash needed to fund working capital or capital expenditures necessary to sustain business operations. This oversight might lead investors to overestimate the available cash for distributions or reinvestment.
- Ignores Cost of Capital Assets: By excluding depreciation and amortisation, EBITDA can overstate earnings, particularly in capital-intensive industries such as manufacturing and telecommunications. In these sectors, ongoing maintenance capital expenditure and the depreciation of expensive machinery and equipment can significantly impact financial results.
- Tax and Interest Obligations: Ignoring taxes and interest can mask real costs that affect the net income of a company. For example, a company with high debt might appear more profitable on an EBITDA basis than it truly is, potentially misleading stakeholders about its financial health.
Additional Considerations for EBITDA’s Limitations
When using EBITDA as a financial metric, it is crucial to consider these additional factors:
- Non-operating Income: EBITDA does not consider earnings or losses from non-operating activities, which can include gains or losses from foreign exchange, investments, or asset sales. This exclusion can lead to an incomplete picture of a company’s overall financial performance.
- Variable Interest Rates: When interest rates are volatile, the exclusion of interest expenses in EBITDA calculations can result in a view of earnings that differs markedly from net profit and cash obligations. This variability can complicate long-term financial planning and debt management strategies.
By understanding these limitations, stakeholders can better assess when EBITDA may provide useful insights and when it might require supplementary information to obtain a full picture of a company’s financial health. This balanced approach aligns with the principle that financial communications should be fair, clear and not misleading.
A Financial Adviser Can Help
Understanding and effectively using EBITDA within your business or investment strategy requires a nuanced approach, given its benefits and limitations. A qualified professional can help you interpret these figures within the context of broader financial analysis and strategy. This information is provided for educational purposes and does not constitute personal advice.
If you decide to seek professional support, consider engaging an FCA-authorised financial adviser or a chartered accountant with corporate finance experience. Check the firm’s status on the FCA Register and ensure the scope of services, fees and any potential conflicts are explained clearly before proceeding.
FinancialAdvisers.co.uk can connect you with an adviser authorised and regulated by the FCA. These professionals can provide advice tailored to your goals and circumstances so you can make informed decisions about your property finance. This article is for information only and does not constitute personal advice.
This article contains external links for further information on topics. Whilst all attempts are made to verify the trustworthiness of these external sources, we accept no responsibilty for the upkeep or security of these external websites. Some of these links in particular are annotated below: